Off plan payment plans explained: 50/50, 60/40 and post handover
Every off plan project in Dubai is sold on a payment plan, and the plan shapes your cash flow, your risk and your exit more than the headline price does. We explain what 50/50, 60/40 and post handover plans mean, what the law says happens to your money, and how to read a plan before you sign.
This article discusses regulation and costs that can change. Confirm current requirements with the relevant authority before acting.
The payment plan is the part of an off plan purchase that buyers spend the least time on and that affects them the most. The price sets what you pay. The plan sets when you pay it, how much of your capital is exposed while the building goes up, and what position you are in if the market, the developer or your own circumstances change before handover. This article explains the structures you will meet in Dubai, what the law says happens to the money, and how we read a plan before we recommend one.
This is general information about the Dubai market as at 5 November 2026, not financial or legal advice. Every plan is set by the developer and written into the sale and purchase agreement, which is the document that binds you.
How to read a ratio
Developers describe plans as a ratio: 50/50, 60/40, 40/60, 70/30. The first figure is the share of the price paid before handover. The second is the share paid at handover or, in a post handover plan, after it. A 60/40 plan therefore means 60% of the price is paid during construction and 40% is due when you receive the keys.
The first figure is the one to watch. It is the share of your capital that is in the project while the project is still a building site. A 70/30 plan has you paying 70% before you can see the finished unit. A 40/60 plan has 40% in and 60% waiting.
Inside that first figure there is a booking amount, paid at reservation and on signing, and a run of instalments. Those instalments are either tied to dates, for example every six months from a stated month, or to construction milestones, for example 10% on completion of the structure. Date based schedules are more predictable for your cash flow. Milestone based schedules are slower when construction is slow, which can suit a buyer who is not in a hurry.
What the market is actually offering
We keep a payment plan on file for every project we market where the developer has published one. On 5 November 2026 that was 61 projects, 60 of them with the plan confirmed against the developer's own material. Across those plans, 50/50 is the most common structure, with 18 projects, followed by 40/60 with 14, 60/40 with 10 and 70/30 with 8. A handful sit at the extremes: two at 90/10, one at 80/20, and single projects at 30/70 and 25/75. Five developers offer a plan with instalments after handover.
Booking amounts in those plans run from 5% to 30% of the price. Most sit between 10% and 20%.
What that tells you is that the market has settled on a middle. A developer offering 40/60 or better is giving you more of the construction risk; one asking 70/30 or more is keeping less of it. Neither is wrong. The price, the developer's record and the community should decide, with the plan read alongside them rather than instead of them.
Post handover plans
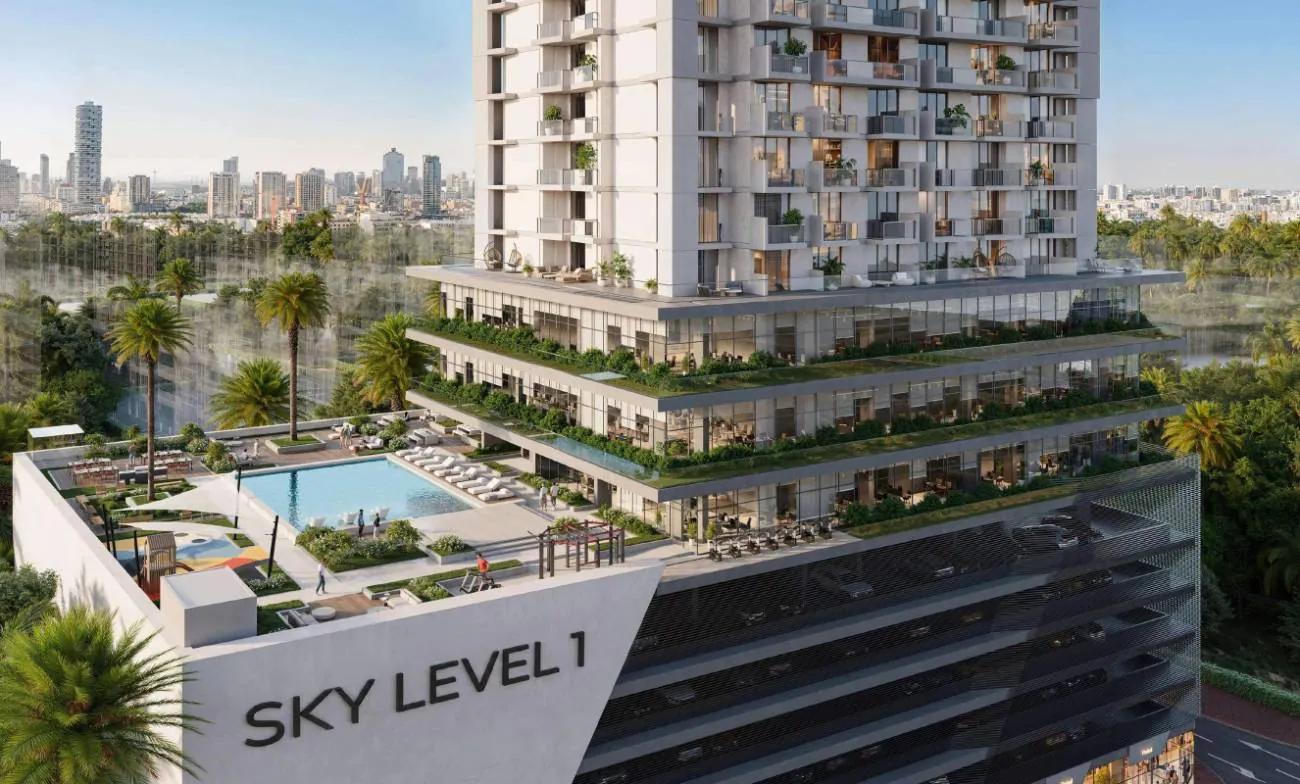
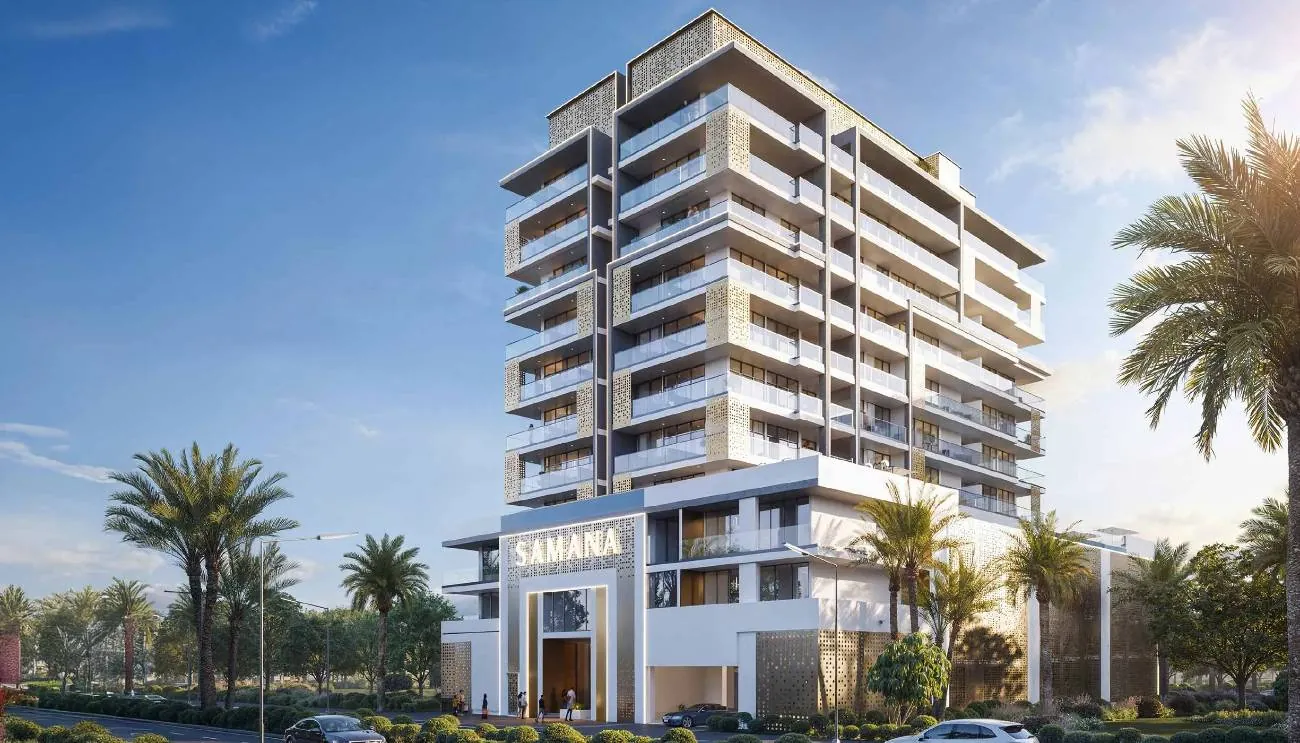
A post handover plan continues the instalments after you receive the keys. Among the projects in our catalogue, Sky Level 1 by Object 1 in Jumeirah Village Circle offers 40/30/30: 20% on booking, 20% during construction, 30% on handover and 30% two years after. Tiger Sky Tower in Business Bay offers 20% on booking, 40% during construction, 10% on handover and 30% over the two years after. Ocean Crest by SAMANA on Dubai Islands offers 60/40 with the 40% after handover. These figures are as published by each developer, and the full schedules are on each project page.
The attraction is clear. From handover, the unit can be let, and rental income can meet part of the remaining instalments while your capital stays available. The trade offs are just as clear. You own a property you have not fully paid for. Until the final instalment the developer retains an interest, which affects whether you can sell, how a buyer's bank views the unit, and whether you can raise a mortgage against it. If the rental market softens or your own income changes, the instalments continue. Treat a post handover plan as a financing arrangement from the developer and compare it on those terms: what is the total you pay, over what period, and what does it cost you in flexibility.
Where the money goes
Dubai requires off plan payments to be made into an escrow account opened for that project. As published by the Government of Dubai in Law No. 8 of 2007, accessed on 5 November 2026, the developer must deposit all amounts paid by purchasers into the project's escrow account, and the account's funds are dedicated to the construction of that project. The account trustee releases funds to the developer in line with the stage of construction, and 5% of the total is retained for one year after the project is registered as complete, to cover defects.
Two practical consequences follow. First, pay only into the escrow account named in your agreement, never to an individual, a sales office or an intermediary. Second, escrow protects the money from being spent on something else; it does not guarantee that the building will be finished on the date in the brochure or to the standard in the renderings. Delay is a construction risk, and escrow does not remove it.
The Dubai Land Department's Project Status enquiry in the Dubai REST application shows a project's registration, its escrow bank and its reported completion percentage. We check it before any client pays a booking amount.
Registration and the 4%
Every off plan sale must be registered in the interim real property register. As published by the Government of Dubai in Law No. 13 of 2008, a sale that is not registered is void. The developer registers the sale through the Dubai Land Department's Oqood system, and DLD states that the contract must be registered within 90 days of signing. DLD lists the registration fee as 2% of the sale value for each party, 4% in total, and the sale and purchase agreement states who bears it. Dubai agreements commonly place the full 4% on the buyer, payable with the booking amount, so check your agreement and put the fee in your cash flow for the first month rather than at handover.
What happens if you stop paying
The payment plan is a schedule you have agreed to, and the law gives the developer a defined route if you fall behind. As published by the Government of Dubai in Law No. 19 of 2017, accessed on 5 November 2026, which replaced Article 11 of Law No. 13 of 2008, the developer notifies the Dubai Land Department of the default, and DLD serves the buyer a 30 day written notice to perform. DLD may also mediate a settlement, which is attached to the agreement.
If the 30 days pass without payment or settlement, DLD issues a document confirming the procedure was followed and stating the project's completion percentage, and the developer may act without a court or arbitration order, according to that percentage:
- More than 80% complete. The developer may keep the agreement and claim the balance, ask DLD to sell the unit at public auction with the buyer bearing the costs, or terminate and retain up to 40% of the contract value.
- Between 60% and 80% complete. The developer may terminate and retain up to 40% of the contract value.
- Less than 60% complete, with work started. The developer may terminate and retain up to 25% of the contract value.
- Work not started, for reasons outside the developer's control. The developer may terminate and retain up to 30% of the amounts actually paid, refunding the rest within 60 days.
In the first three cases, any amount above the retained share must be refunded within one year of termination or within 60 days of the unit being resold, whichever comes first.
The figures matter because the retention is calculated on the contract value, not on what you have paid. A buyer on a 50/50 plan who has paid 30% and defaults when the building is 65% complete can lose everything paid and still be short of the 40% the developer may retain. Before committing to any plan, run the schedule against your own cash flow for the full construction period and allow for a handover that arrives a year later than planned.
Delay and your instalments
Sale agreements normally allow the developer a grace period beyond the anticipated completion date before the buyer has any remedy, and the length of that period is set in each agreement. Date based instalments continue during that period. If your plan has a large payment due "on handover", a delay defers that payment, which can help; if your plan is date based, a delay means you keep paying for a unit you cannot yet use. Read the anticipated completion date, the grace period and the instalment trigger together, because the three decide what a delay costs you.
How we compare plans
When two projects compete for the same client we lay the plans side by side on four points.
- Exposure during construction: the share paid before handover, and when the largest instalments fall.
- Total cost: the price plus the 4% registration fee, any administration fees in the agreement, and, for a post handover plan, the full amount over the full period.
- Flexibility: whether the unit can be resold before handover, and after what percentage paid, and whether the plan can be settled early.
- Resilience: what the schedule looks like if handover is twelve months late, and what the buyer stands to lose under Article 11 at each stage of completion.
Every project page on this site shows the developer's published plan, phase by phase, with the status "Developer confirmed" where we have verified it against the developer's own material. Where a plan reads "To be confirmed", ask us for the current schedule before relying on it.
Our view
The best plan is the one that matches your money, not the one with the smallest number at the front. A buyer with capital ready and a long horizon can take a 70/30 plan on a strong project at a better price. A buyer who wants to keep capital working elsewhere, or who intends to let the unit from day one, should look hard at 40/60 and post handover structures and price the flexibility they are paying for. In both cases, the agreement, the escrow account and the Dubai REST project record are the documents that count, and we read all three before a client signs.
Questions and answers
What does a 60/40 payment plan mean?
Is my money protected while the project is being built?
What happens if I stop paying?
Are post handover plans worth it?
Sources
- Article 11 as replaced by Law No. 19 of 2017, purchaser default procedure, 30 day notice, retention bands of 40%, 25% and 30% (opens in a new tab). Government of Dubai, Supreme Legislation Committee. Accessed .
- Explanatory Notes on Article 11 of Law No. 19 of 2017 (opens in a new tab). Government of Dubai, Supreme Legislation Committee. Accessed .
- Escrow account obligations, use of funds and 5% retention (Articles 6, 7, 9, 14, 15, 16) (opens in a new tab). Government of Dubai, Supreme Legislation Committee. Accessed .
- Interim register, void unregistered sales, approvals before selling (Articles 3, 4, 10, 11) (opens in a new tab). Government of Dubai, Supreme Legislation Committee. Accessed .
- Initial sale registration through Oqood, fees, 90 day registration condition (opens in a new tab). Dubai Land Department. Accessed .
- Project Status (Mashrooi) enquiry in Dubai REST, including escrow bank details and completion percentage (opens in a new tab). Dubai Land Department. Accessed .
- Castilion Estates project catalogue, payment plans as published by each developer, 61 projects with a plan on file (opens in a new tab). Castilion Estates. Accessed .
Where Castilion can help
- Investment advisoryEvidence based advice for long term holders.
- Asset protection and structuringHow to hold property in the UAE.
Weighing a decision this touches?
Our licensed team can talk it through with you, in confidence and without obligation.
Talk to an Advisor